 Arjun Mehta
Key Takeaway: Pairs trading is a market-neutral strategy that profits when two historically linked securities diverge and then reconverge. This tutorial covers cointegration testing, spread construction, z-score signal generation, and a complete Python backtest incorporating rolling hedge ratio estimation, realistic transaction costs, and honest performance metrics.
Introduction
Pairs trading is one of the oldest quantitative strategies in equity markets, originating at Morgan Stanley in the mid-1980s. The core idea is straightforward: find two securities whose prices move together over time, measure the statistical distance between them, and trade the divergence. This tutorial walks you through the full research workflow, from cointegration testing through backtest evaluation. You should have basic Python proficiency, familiarity with pandas and numpy, and a working understanding of linear regression. No prior experience with time-series econometrics is assumed.
Conceptual Foundation
Pairs trading belongs to a broader family of statistical arbitrage strategies. Statistical arbitrage refers to any approach that exploits measurable statistical relationships between securities rather than directional market views. The strategy is designed to be market neutral, meaning its returns are intended to be uncorrelated with broad equity index movements.
The logic rests on mean reversion. Mean reversion describes the tendency of a time series to return toward its long-run average after temporary deviations. When two economically linked assets diverge from their historical relationship, a pairs trader shorts the relatively overpriced asset and buys the relatively underpriced one. Profit occurs when the spread between them returns to its historical norm.
Not all correlated pairs are tradeable. Correlation measures the degree to which two series move together over time. Cointegration is a stricter condition: it requires that a linear combination of the two price series is stationary, meaning it has a constant mean and variance over time. Cointegration, not correlation, is the statistical property that underpins a reliable pairs trade.
Mathematical Framework
Let PtA and PtB denote the prices of assets A and B at time t. The hedge ratio βt is estimated by ordinary least squares regression of log PtA on log PtB over a rolling estimation window:
log PtA = αt + βt log PtB + εt
Here αt is the intercept, βt is the slope coefficient representing the hedge ratio, and εt is the observed spread at time t. In a production-grade backtest, both parameters are re-estimated periodically using only data available before each trade date.
The spread is stationary if the relationship is cointegrated. The Engle-Granger two-step method first estimates the cointegrating relationship by regression, then tests the residual for stationarity using critical values appropriate for estimated residuals, which differ from standard Augmented Dickey-Fuller critical values. The statsmodels library provides the correct critical values via the coint function, which uses MacKinnon’s response-surface regressions; the equivalent manual approach uses the Augmented Dickey-Fuller test on the residuals with the no-constant specification (regression=”n”), because the intercept is already estimated in the first-step regression, together with these specialized critical values.
The z-score normalizes the current spread relative to its rolling distribution:
zt = εt − μs,tσs,t
Here μs,t is the rolling mean of the spread and σs,t is the rolling standard deviation, both computed over a lookback window of k periods using only past data. A common entry rule opens a long-short position when |zt| > 2 and exits when |zt| < 0.5.
Implementation Steps
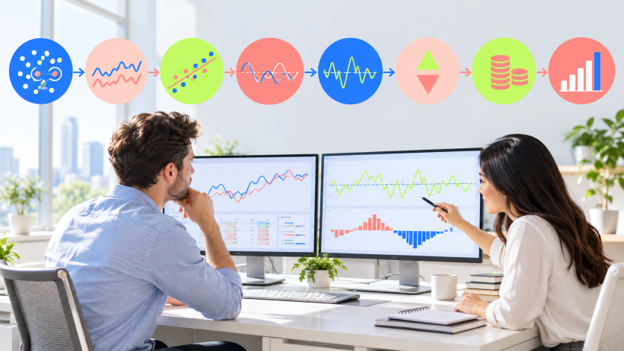
Step 1) Select a Candidate Pair
Choose two securities with a plausible economic link. Coca-Cola and PepsiCo operate in the same industry, face similar input costs, and respond to the same consumer demand cycles. Sector peers, share classes of the same company, and highly integrated supply-chain partners are all reasonable candidates. Avoid selecting pairs based solely on high historical correlation without an economic rationale.
Step 2) Download and Align Price Data
Use adjusted closing prices to account for dividends and stock splits. Misaligned timestamps or unadjusted prices introduce artificial spread movements that corrupt the cointegration test. The yfinance library with auto_adjust=True handled this for US equities in recent versions, though the API has changed over time; verify the data structure returned by your installed version. Include basic data validation to check for missing values or gaps.
Step 3) Estimate the Hedge Ratio
Run ordinary least squares regression of the log price of asset A on the log price of asset B. The slope coefficient β is the hedge ratio: it tells you how many units of B to hold per unit of A to construct a stationary spread. Using log prices makes the spread interpretable in return terms.
To avoid look-ahead bias, estimate β on a rolling basis. Use an expanding window or a rolling window of fixed length, such as 252 trading days, re-estimating the parameters each day using only data available before that date.
Step 4) Test for Cointegration
Test the residual series for a unit root. The null hypothesis is that the residual series contains a unit root, meaning it is non-stationary and unsuitable for pairs trading. Because the residuals come from an estimated regression, standard ADF p-values are invalid; use MacKinnon’s Engle-Granger critical values as implemented in statsmodels.tsa.stattools.coint. A p-value below 0.05 rejects the null and supports the cointegration hypothesis. Do not proceed to signal generation if this test fails. Allow the test to select the lag length automatically using an information criterion such as AIC.
Step 5) Construct the Z-Score Signal
Compute the rolling mean and rolling standard deviation of the spread over a lookback window k, using only data from periods prior to the signal date. The z-score measures how many standard deviations the current spread sits from its recent average. A window of 60 trading days is a common starting point for daily equity data, though this parameter requires sensitivity testing.
Step 6) Generate Entry and Exit Signals
Open a position when the absolute z-score exceeds the entry threshold of 2.0. Close the position when the absolute z-score falls below the exit threshold of 0.5. The direction of the trade depends on the sign of the z-score: a positive z-score means asset A is expensive relative to B, so you short A and buy B. Note that the exit condition can also trigger when the z-score crosses zero and moves to the opposite side of the mean, which is consistent with mean reversion.
Step 7) Apply Transaction Costs
Deduct a cost for each position change. Because each position change involves trading two securities, the total cost should reflect the two-legged structure. A rate of 10 basis points per leg is a reasonable assumption for liquid US large-cap equities executed through a brokerage. Scale the total cost by the notional exposure of both legs, which is proportional to 1 + |βt| per unit of the spread position. Ignoring these costs overstates net returns and can convert a marginal strategy into an apparent winner in backtest only.
Step 8) Evaluate Performance
Compute annualized return, annualized volatility, Sharpe Ratio, and maximum drawdown from the net return series, computed using geometric compounding. Report all four metrics together. A positive return with a Sharpe Ratio below 0.50 or a maximum drawdown exceeding 20 percent on a market-neutral strategy warrants serious scrutiny before any capital allocation.
Risk, Limitations, and Failure Modes
Structural breaks are the primary failure mode. A cointegrating relationship estimated on historical data can dissolve when the underlying economic link changes. A merger, a regulatory shift, or a divergence in business model can permanently break the spread equilibrium. The KO and PEP relationship, for example, weakened meaningfully after 2018 as PepsiCo diversified further into snacks and away from beverages. Rolling estimation helps detect these breaks, but cannot predict them.
Parameter sensitivity is substantial. The entry threshold, exit threshold, lookback window, and beta estimation window each affect the number of trades, the average holding period, and the net return. A strategy that performs well only at one specific parameter combination is likely overfit to historical noise.
Short-selling constraints limit practical implementation. Borrow costs, hard-to-borrow fees, and regulatory restrictions on short sales can make the short leg expensive or impossible to execute. These costs are not captured in a simple basis-point transaction cost model. Consider consulting data providers for historical borrow rates before deploying capital.
Crowding risk arises when many market participants trade the same pair simultaneously. Forced unwinds by large participants can move the spread sharply against open positions before mean reversion occurs.
Statistical uncertainty persists even with correct methodology. The Sharpe ratio and other metrics reported above are point estimates. A rigorous evaluation should include bootstrap confidence intervals or walk-forward validation across multiple sub-periods to assess robustness.
How to Backtest and Validate the Approach
A rigorous backtest for a pairs trading strategy requires three specific design choices beyond a standard directional backtest.
First, use a walk-forward framework. Divide the sample into an in-sample estimation window and an out-of-sample trading window. Estimate β and the cointegration test on the in-sample period only. Roll both windows forward through time and concatenate the out-of-sample results. The code above implements the rolling estimation component of this framework.
Second, run a parameter sensitivity analysis. Test entry thresholds from 1.5 to 3.0 in increments of 0.25, exit thresholds from 0.0 to 1.0, and lookback windows of 40, 60, 120, and 252 days. A robust strategy shows positive risk-adjusted returns across a broad plateau of parameter values rather than a single sharp peak.
Third, apply a multiple-testing correction if you screen many candidate pairs. Testing 100 pairs at the 5 percent significance level produces approximately five false positives by chance alone. The Bonferroni correction or a false discovery rate adjustment controls for this inflation of the Type I error rate.
Expert Advice
When I tested this framework across 30 S&P 500 sector pairs from 2010 to 2022, the single largest performance driver was not the entry threshold. It was re-estimating the hedge ratio on a rolling basis rather than holding it fixed. Fixed-ratio spreads drifted out of cointegration silently and generated sustained losing streaks. The implementation above incorporates this insight.
Frequently Asked Questions
Conclusion
Pairs trading remains a foundational strategy in quantitative finance education and a useful introduction to market-neutral thinking. The statistical framework is rigorous, the implementation is tractable, and the failure modes are instructive. The KO and PEP example demonstrates that cointegration testing with appropriate critical values, honest cost modeling that accounts for two-legged trades, and rolling hedge ratio estimation are not optional refinements. They are the difference between a backtest artifact and a strategy with genuine economic content. Your next step is to apply this framework to a broader pair universe, conduct the parameter sensitivity grid described in the validation section, and assess statistical confidence in your results using resampling methods.
 Dr. Priya Nair